Small businesses should adopt AI where it removes repetitive work and improves visibility, not where it creates an impressive demo. The constraint is usually not access to models. It is the absence of a clear process owner, a reliable source of truth and a simple control framework.
Begin with low-regret workflows: drafting customer replies, classifying incoming documents, preparing a first-pass sales summary, reconciling routine transactions and turning approved data into a weekly dashboard. Avoid automating payments, statutory filings or final commercial decisions until exceptions, approvals and evidence are explicit.
A lightweight AI control framework has six parts: approved tools, approved data classes, named owners, human approval points, logging and a monthly review. A customer-support assistant may read a knowledge base but should not invent refund terms. A finance workflow may suggest a match but should route uncertain transactions to a reviewer.
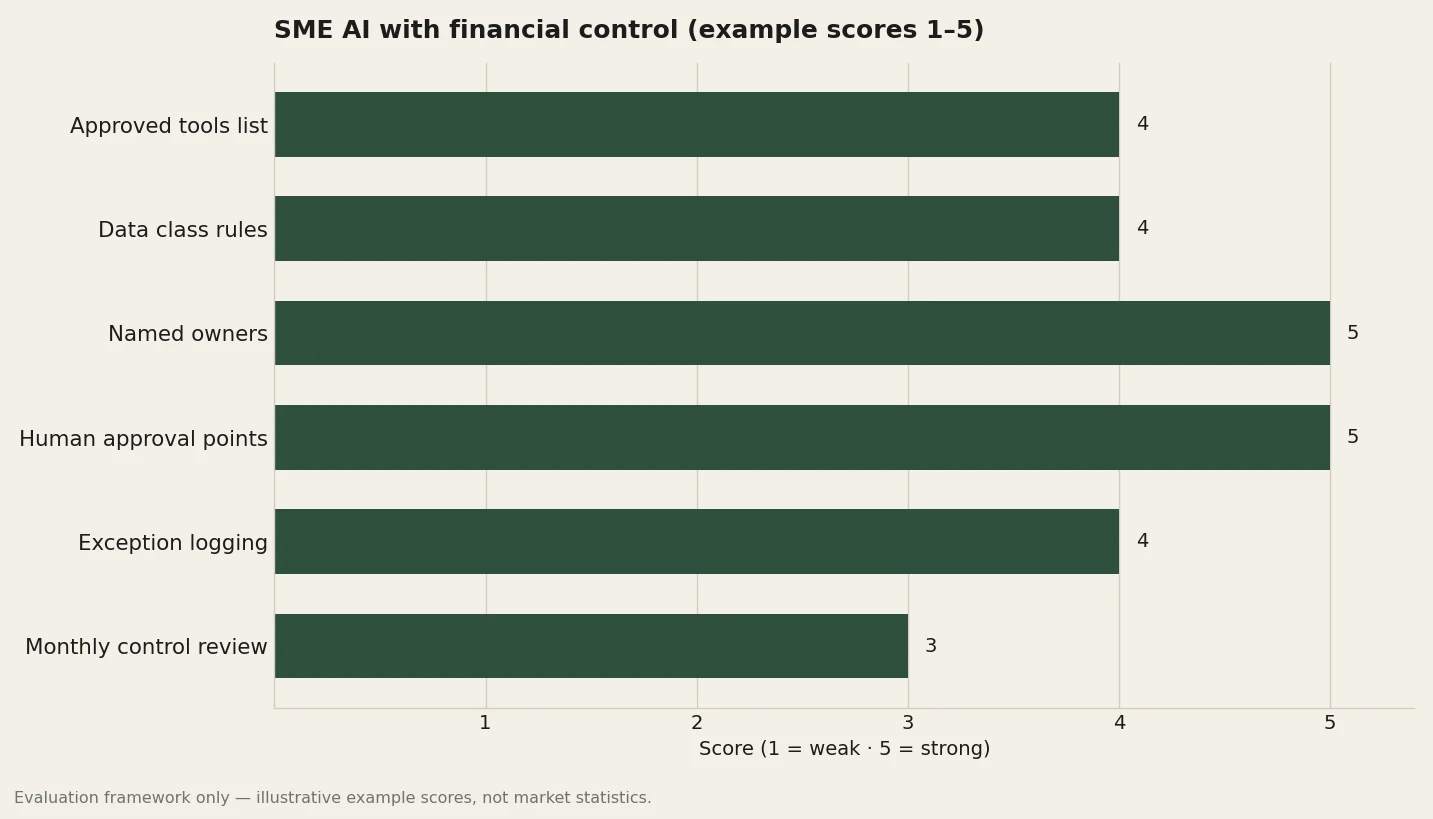
Decision rubric (score 1–5 yourself)
Score each row before expanding AI into cash-impacting workflows. Under about 18: keep AI in draft-only mode. Above about 22 with named owners: carefully widen scope.
| Axis | 1 = weak fit | 5 = strong fit | Your score |
|---|---|---|---|
| Approved tools list | Anyone can paste data anywhere | Short approved stack with owners | ___ |
| Data class rules | No distinction of sensitive data | Clear rules for customer and financial data | ___ |
| Named owners | Automation “belongs to everyone” | Each workflow has a responsible person | ___ |
| Human approval points | Straight-through on money and filings | Explicit hold points for cash and compliance | ___ |
| Exception logging | Errors disappear in chat | Exceptions aged and reviewed | ___ |
| Monthly control review | No recurring review | Fixed monthly control and tool review | ___ |
Metrics and tool spine
Track cycle time, rework, error rate, unresolved exceptions and cash-impacting delays. HubSpot can provide a customer and pipeline operating spine, Notion can hold SOPs and decision records, and Synder can be evaluated for commerce-to-accounting synchronisation. None removes the need for reconciliations, access controls or management review.
The practical sequence is to document the workflow, choose one measurable bottleneck, configure the smallest useful automation, run it in parallel, review exceptions and only then expand. NIST’s AI Risk Management Framework offers a voluntary structure for mapping and managing AI risks that scales down well for SMEs that prefer clarity over theatre.
Monday-morning checklist
- Publish the approved tools list and data classes for this month.
- Confirm named owners for each AI-assisted workflow.
- Age the exception list: anything cash-impacting gets a date and owner.
- Spot-check one automated output against the source system of record.
- Cancel or restrict one tool that lacks an owner or a metric.
What not to automate yet
Do not automate payment releases, tax filings, payroll finalisation, contractual commitments or customer promises that create refund or liability exposure until controls are written and tested. Draft assistance is fine; silent authority is not. If a workflow can move cash or create a regulatory filing, require a human hold point with evidence retained.
Train the team with examples of correct and incorrect use. A short SOP beats a long policy nobody reads. Review monthly: what ran, what failed, what was overridden, and whether the metric justified the risk.
Common failure modes
Pasting financial data into unapproved tools. Automating before reconciliations exist. Measuring “AI adoption” instead of exception ageing. Letting marketing buy tools that finance cannot control. Avoidance is a short approved list, named owners, and a monthly control review on the calendar.
What this guide is not
This article is educational and does not constitute accounting, tax, legal or investment advice. Confirm product pricing, data-processing terms and affiliate status before purchase.
How to review progress after four weeks
At the end of a controlled trial, write a one-page note a sceptical finance partner can read. Cover what you attempted, what evidence you produced, what changed in operating behaviour, and whether the tool or workflow should be renewed, narrowed or cancelled. Prefer concrete artefacts — decision logs, exception lists, shipped actions — over vanity dashboards. If you cannot produce that note, the experiment is incomplete regardless of how impressive demos looked.
Carry forward only the workflows with a named owner and a metric you already manage. Archive unused seats, unused templates and unused tracking lists. Tool sprawl is a quiet tax on attention; a shorter stack with weekly discipline usually beats a broad stack that nobody operates.
How to review progress after four weeks
At the end of a controlled trial, write a one-page note a sceptical finance partner can read. Cover what you attempted, what evidence you produced, what changed in operating behaviour, and whether the tool or workflow should be renewed, narrowed or cancelled. Prefer concrete artefacts — decision logs, exception lists, shipped actions — over vanity dashboards. If you cannot produce that note, the experiment is incomplete regardless of how impressive demos looked.
Carry forward only the workflows with a named owner and a metric you already manage. Archive unused seats, unused templates and unused tracking lists. Tool sprawl is a quiet tax on attention; a shorter stack with weekly discipline usually beats a broad stack that nobody operates. Put the renew/kill decision on the calendar so it is not postponed by another shiny pilot.
If the note shows partial value, narrow scope rather than expanding seats. Keep the one workflow that moved a metric, document the SOP, and pause everything else. Partial success is still success when it becomes an operating habit instead of a slide in a quarterly update.